Key Takeaways
- Clean, organized loan packages boost credibility and speed up lender decisions.
- Addressing lender myths and evolving expectations can significantly improve outcomes.
Pitching lenders starts with assembling a compelling, clean loan package and knowing what matters most in today’s lending landscape. By separating fact from fiction and following proven frameworks, you can increase your effectiveness and credibility with lenders in 2026.
What Is a Clean Loan Package?
Core components of a clean package
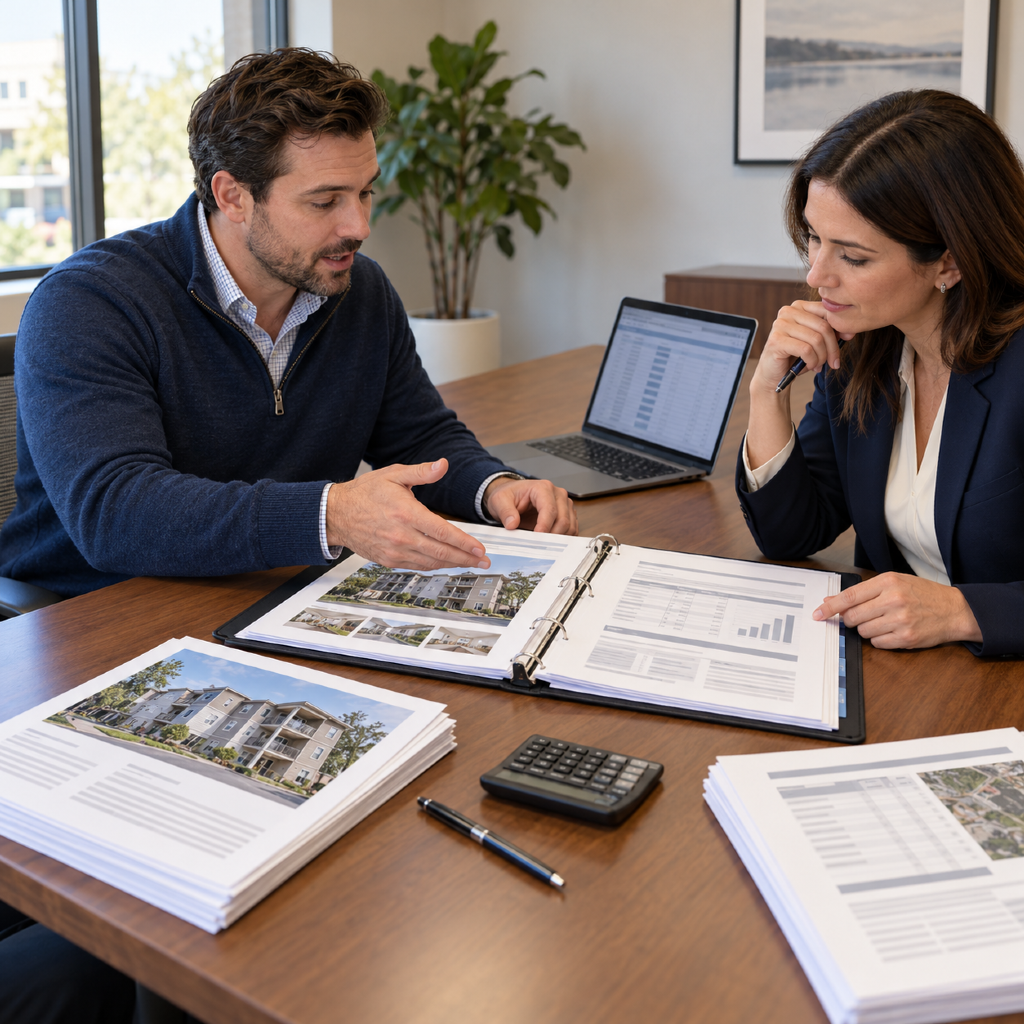
A clean loan package is a carefully structured presentation of all the documentation a lender needs for underwriting and risk assessment. Essential components include up-to-date financial statements (such as profit and loss, balance sheets, and cash flows), a concise executive summary, borrower bios, entity documents (e.g., LLC operating agreements), relevant property information, existing debt details, and third-party reports (appraisals, inspections, or environmental assessments).
Clear labeling, logical organization, and including only necessary documents are vital. If your package is digital, consistent naming conventions and a straightforward folder hierarchy help lenders navigate without confusion.
Why lenders value clean documentation
Lenders rely on clean documentation to save time, reduce errors, and make more informed decisions. A well-prepared package communicates your professionalism and attention to detail. Ultimately, this expedites approvals, reduces back-and-forth questions, and shows you have a strong command of your project or deal.
Why Do Lenders Reject Packages?
Common pitfalls in submissions
Many loan packages are rejected simply because of missing documents, inconsistencies, or unclear information. Common pitfalls include outdated financials, insufficient explanations for financial anomalies, missing signatures, or failure to address lender-specific requirements. Submitting excessive documentation that obscures key facts can also delay or lead to denial.
Misconceptions about lender criteria
A frequent misconception is that more documentation always increases your chance of approval. In reality, lenders prioritize clear, accurate, and relevant materials. Another myth is that lenders consider only the numbers; in practice, qualitative factors—such as borrower track record, project feasibility, and market context—often play an important role in decision-making.
Which Pitch Strategies Actually Work?
Evidence-based presentation techniques
Start by framing your pitch with a clear executive summary that outlines the transaction, the amount requested, and critical project highlights. Organize supporting documents logically, lead with the most important information, and use charts or tables to visualize key financials. Referencing market data and recent comps strengthens your presentation without overcomplicating it.
Communicating strengths transparently
Authenticity and transparency are essential. Clearly present both the deal’s strengths and any challenges, along with mitigation strategies. Lenders appreciate borrowers who anticipate questions and proactively address potential concerns—for example, by explaining income variability or showing contingency plans for market shifts.
Step-by-Step: Building a Clean Package
Organizing essential documentation
Begin by assembling foundational documents: the executive summary, business or project plan, up-to-date financial statements, ownership/organizational charts, current rent rolls (if applicable), and due diligence reports. Use a checklist tailored to your lender’s stated requirements and avoid including documents that have not been specifically requested unless they directly clarify key points.
Highlighting risk factors and mitigations
Identify clear risk factors (e.g., short lease rollovers, deferred maintenance, borrower experience gaps) and address them with direct, data-driven mitigation strategies. For example, if market lease rates are softening, outline your contingency reserves or tenant diversification plans—showing lenders you have considered and planned for risks.
Tips for clear financial summaries
Your financial summaries should be concise, consistently formatted, and supported by current data. Use summary tables for high-level overviews, attach explanatory notes for any non-obvious figures, and ensure that line items align across all financial documents. Annotations or footnotes can clarify year-over-year variances or one-time expenses that might otherwise seem concerning.
What Are Common Myths About Lender Pitches?
Myth: More documents always help
It’s easy to believe that over-documenting a package will impress lenders. In reality, too much irrelevant information can bury what matters and may frustrate reviewers. Focus on completeness and relevance, rather than volume.
Myth: Personal guarantees assure approval
While personal guarantees show commitment, they don’t guarantee a positive lending decision. Lenders still assess the underlying deal fundamentals, borrower experience, and market risks. Use guarantees strategically—highlighting them alongside, not instead of, solid project fundamentals.
How Do Lender Expectations Evolve?
Trends since 2025
Lender expectations have increasingly shifted toward digital-first, organized submissions. Since 2025, lenders have also paid more attention to borrower operational competence and adaptability to volatile market conditions. Lenders now use clear, data-backed business plans and risk management sections as key indicators in preliminary evaluations.
Technology’s impact on underwriting
Automation and artificial intelligence continue to transform lender evaluation processes. Digital intake platforms automatically cross-check data, flag inconsistencies, and accelerate preliminary reviews. As a result, well-structured, error-free submissions stand out, while sloppiness or omissions are caught quickly and can lead to immediate rejection or delays.
What Risks Should Investors Consider?
Potential pitfalls in lending negotiations
Even with a well-prepared package, negotiations can be complex. Terms may shift based on lender risk appetite, macroeconomic developments, or changes in collateral value. Avoid overcommitting or overlooking fine print in proposed terms.
Acknowledging changing market conditions
Real estate investing in 2026 remains exposed to cyclical risks and evolving lender standards. Be prepared for more rigorous stress-testing of assumptions and for lenders to ask probing questions about exit strategies, cash flow projections, and contingency planning. Acknowledging risks transparently builds confidence and trust with your lending partners.
FAQ: Pitching Lenders in 2026
How to follow up after submission?
Following up professionally is important. Allow sufficient time for the lender to review (often 3–7 business days), then send a concise email or message expressing appreciation and offering to clarify any points. Avoid excessive contact, and always remain courteous and helpful—this fosters a positive working relationship for the current and future transactions.
What if a package is rejected?
Rejection is not final. Request constructive feedback and review your submission for gaps or points that may require greater clarification. Use this feedback to update and strengthen your package before resubmitting or approaching alternative lenders. Persistence, paired with a commitment to learning and revising, often leads to better outcomes over time.